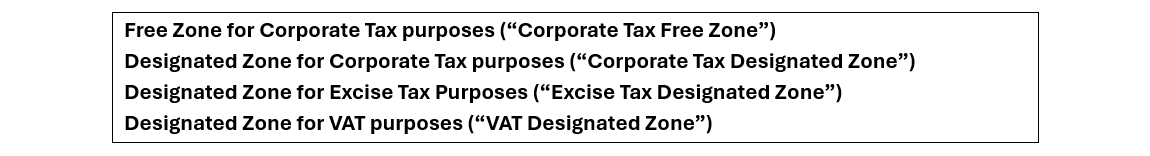
There are differences in the definition of a Free Zone or a Designated Zone for Corporate Tax, Excise Tax, and Value Added Tax.
Businesses must determine if they are located in an area that qualifies as a Free Zone and/or Designated Zone for each Tax Law separately in order to be compliant with the relevant rules and regulations.
Corporate Tax Free Zone
A Corporate Tax Free Zone is a designated and defined geographic area within the UAE that is specified in a decision issued by the Cabinet at the suggestion of the Minister.
Corporate Tax Designated Zone:
- A VAT Designated Zone is not automatically a CT Designated Zone.
- The zone must be recognised as both a VAT Designated Zone and a CT Free Zone.
Excise Tax Designated Zone:
Any fenced area established as a free zone that cannot be entered or exited except through a designated road, or any area designated by the FTA as being subject to the supervision of a Warehouse Keeper, in accordance with the provisions of the Excise Tax Executive Regulation.
A fenced free zone qualifies if it:
- has security measures restricting entry and exit of individuals and movement of Excise Goods, per FTA controls,
- is controlled and supervised by a customs department, and
- has a Warehouse Keeper appointed.
A non-free-zone geographic area designated by the FTA must:
- be a specified geographic area,
- have security measures restricting entry and exit of individuals and Excise Goods, per FTA controls, and
- have a Warehouse Keeper appointed.
Process:
- The Warehouse Keeper must apply to the FTA to register the area.
- Businesses should confirm with the Warehouse Keeper that the FTA approved it.
- A Warehouse Keeper is a person approved and registered with the FTA to supervise a Designated Zone.
VAT Designated Zone
A VAT Designated Zone is a specific fenced area listed in the List of Designated Zones that meets Article 51(1) of the VAT Executive Regulation.
https://tax.gov.ae/DataFolder/Files/Legislation/Designated%20Zones%20-%2021%2009%202021%20sep21.pdf
It is treated as outside the UAE and outside the Implementing States only if:
- It is a fenced geographic area with security measures and customs controls monitoring entry and exit of individuals and movement of goods,
- it has internal procedures for keeping, storing and processing goods, and
- the zone operator complies with the FTA's procedures.
A company must do both of the following:
- review the FTA's published list, and
- confirm with the Free Zone authority that the Article 51(1) conditions are met for the specific area where it is based.
|
Type |
Meaning |
How to confirm |
|
CT Free Zone |
A designated geographic area in the UAE specified by a Cabinet decision, on the Minister's suggestion |
Check with the Free Zone authority |
|
CT Designated Zone |
A zone on the VAT List of Designated Zones (Cabinet Decision 59/2017 and amendments) and also a Free Zone under the CT Law |
Check with the Free Zone authority |
|
Excise Designated Zone |
A free zone or geographic area meeting the Excise Law and Excise Executive Regulation conditions |
Check with the Free Zone authority or the Warehouse Keeper whether the FTA approved the area |
|
VAT Designated Zone |
A Free Zone listed in Cabinet Decision 59/2017 that meets the Article 51(1) VAT Executive Regulation conditions |
Check the FTA's published List of Designated Zones |
Disclaimer: Content posted is for informational and knowledge sharing purposes only, and is not intended to be a substitute for professional advice related to tax, finance or accounting. The view/interpretation of the publisher is based on the available Law, guidelines and information. Each reader should take due professional care before you act after reading the contents of that article/post. No warranty whatsoever is made that any of the articles are accurate and is not intended to provide, and should not be relied on for tax or accounting advice.
Contributor
CA DRG Mahesh is Chartered Accountant and UAE Tax & Compliance professional with 6+ years of experience across taxation, auditing, accounting, and financial compliance, including 4+ years of UAE experience. Currently working as a Tax and Compliance Manager at Stuart & Hamlyn Chartered Accountants, with expertise in UAE VAT, Corporate Tax, ESR, AML, tax compliance, audits, and financial analysis. Experienced in supporting businesses with corporate tax impact assessments, tax planning and return filing, compliance reviews, internal and external audits, and regulatory guidance. Known for combining technical expertise with a practical, business-focused approach to help organizations manage compliance requirements, minimize tax risks, and achieve sustainable growth.